A toppled crane, an excavator caught in a monsoon flood or a loader stolen from site can wipe out a project's profit in a single day. Contractor's Plant and Machinery insurance exists for these moments, yet many owners only read their policy after a loss, and some see claims cut for reasons they could have prevented. This guide explains what CPM usually covers and excludes, what drives the premium and how claims work. It is general information, so read your own policy wording, and HVI keeps the records that support every claim.
Contractor's Plant and Machinery (CPM) Insurance Guide India
Understand what a CPM policy protects, where the gaps usually are, and how good inspection and maintenance records turn a stressful claim into a smooth one.
- Accidental damage at site
- Overturning and collision
- Fire, lightning and explosion
- Flood, storm and similar perils
- Theft and burglary
- Mechanical or electrical breakdown
- Wear, tear and gradual deterioration
- Consumables like tyres and teeth
- Use on public roads
- Wilful negligence
- Third-party liability
- Earthquake, where not included
- Removal of debris
- Express freight for parts
- Escalation of sum insured
Seven Site Scenarios: Would CPM Pay?
Real situations make the policy easier to understand. These are typical outcomes under standard wordings. Your policy terms decide the actual answer.
Crane overturns while lifting
Accidental overturning at site is a core CPM risk, subject to safe operation and load limits.
Excavator flooded on site
Flood and inundation are usually covered perils, though reasonable precautions are expected.
Loader stolen from site
Theft is usually covered with a police report and the security conditions in the policy met.
Engine seizes from low oil
Internal mechanical breakdown is normally excluded unless a breakdown add-on is taken.
Worn tracks and bucket teeth
Wear and consumables are a maintenance cost, not an insured loss.
Damage to a neighbour's wall
Damage to other people's property needs third-party liability cover.
Backhoe hit while on a highway
Road-registered machines on public roads usually fall under motor insurance, not CPM.
What Drives Your CPM Premium
Insurers price risk. These factors usually make the biggest difference, and several are within your control.
The Under-Insurance Trap
CPM is commonly written on the new replacement value of the machine. If the sum insured is lower than it should be, many policies reduce the claim in proportion. The figures below are illustrative.
How to avoid it
Review the sum insured at every renewal against the current price of an equivalent new machine, and update it after any price rise or upgrade.
Never Miss a Renewal or a Sum Insured Review Again
HVI tracks policy expiry, sum insured review dates and inspection history for every machine, so cover stays current and claim evidence is always ready.
The CPM Claim Process, Step by Step
Speed and evidence decide most claims. Check your policy for exact notice periods and conditions.
Make it safe
Protect people and take reasonable steps to stop further damage.
Inform the insurer
Notify as soon as possible, in writing, with the policy number.
Police report
File an FIR for theft, malicious damage or third-party involvement.
Record evidence
Photos, hour meter, operator details and site conditions.
Survey
Keep the machine available for the surveyor before repairs start.
Repair and settle
Repair after approval and submit bills for settlement.
Why CPM Claims Get Reduced or Rejected
Most problems are avoidable with simple habits and good records.
| Reason | What it looks like | How to prevent it |
|---|---|---|
| Late intimation | Insurer told days or weeks after the event | Report the same day, even before costs are known |
| Damage looks like wear | Surveyor sees neglect, not an accident | Keep dated inspection and service records with photos |
| Unqualified operator | No valid licence or training proof | Record operator details and certificates per shift |
| Under-insurance | Claim cut in proportion to the shortfall | Review sum insured at every renewal |
| Machine not on the policy | New or transferred machine never added | Update the schedule whenever the fleet changes |
| Repairs before survey | Evidence lost before inspection | Wait for the surveyor or get written approval |
Claim Documents Checklist
Keep these ready for every machine. Having them on file before an accident saves days in the claim.
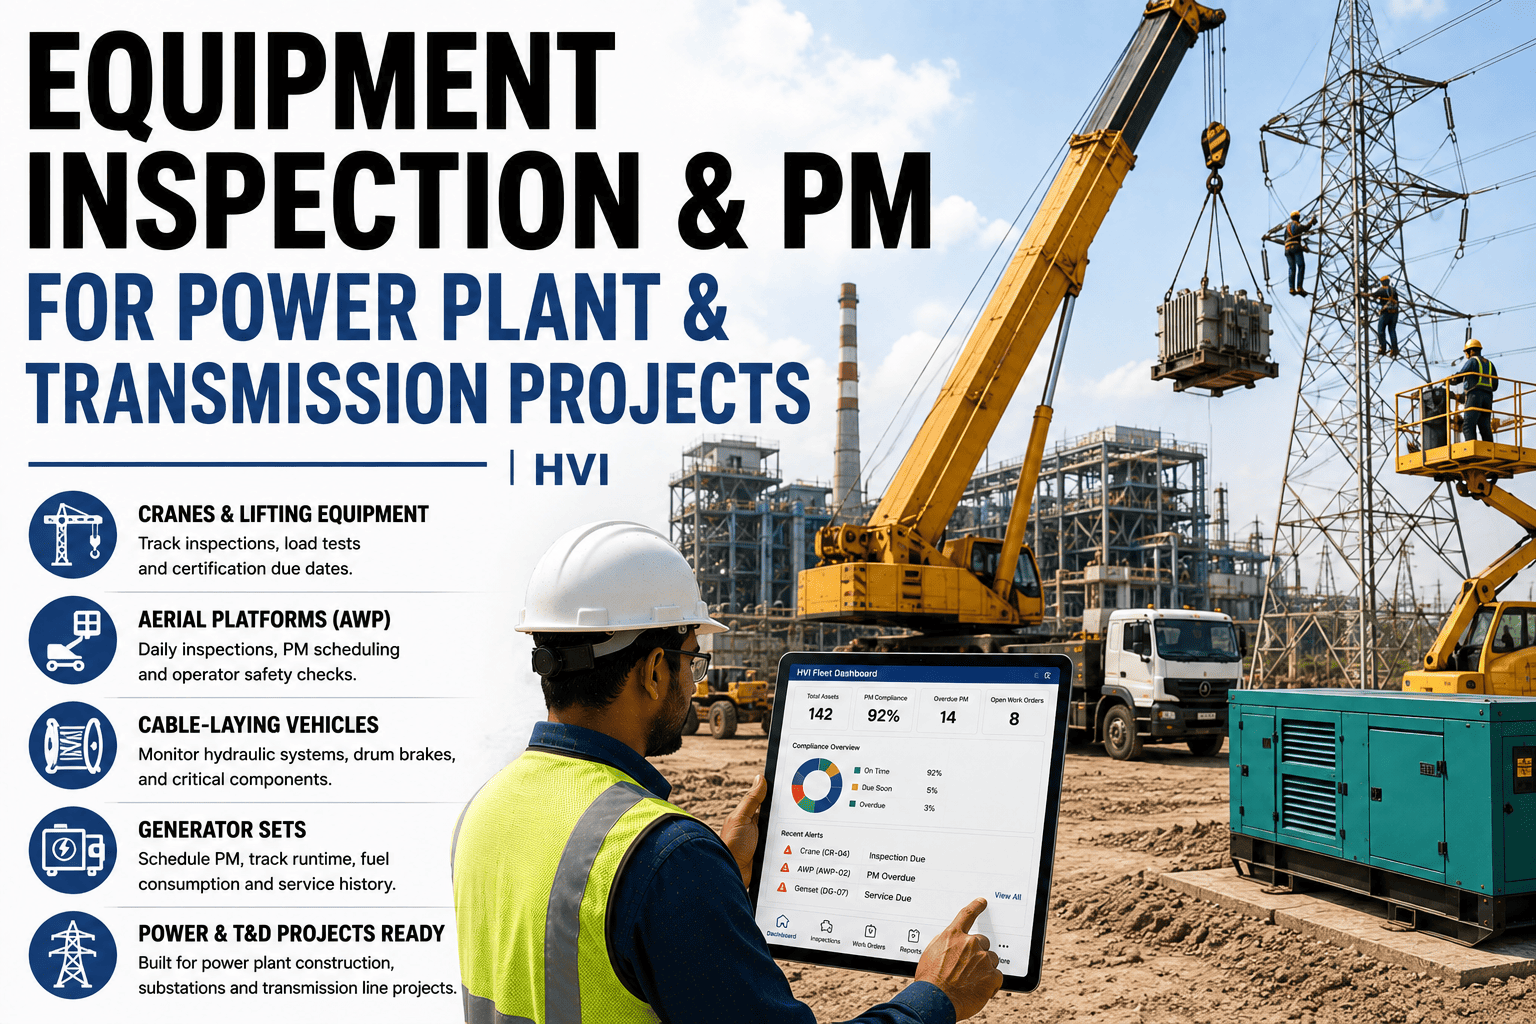
Insurance Readiness for Every Machine in HVI
A sample view. Policy dates sit next to inspection history, so you can see which machines are fully protected and which need attention.
| Machine | Policy expiry | Sum insured review | Last inspection | Readiness |
|---|---|---|---|---|
| CRN-01 | In 4 months | Done this year | 2 days ago | Claim ready |
| EXC-06 | In 18 days | Due | 1 week ago | Renew and review |
| LDR-03 | In 7 months | Done this year | 5 weeks ago | Inspection overdue |
| BHL-02 | Expired | Not done | 3 days ago | Not covered |
CPM Insurance FAQs
What does CPM insurance cover?
CPM insurance usually covers accidental physical loss or damage to construction machinery at site, including overturning, collision, fire, flood, storm and theft. It generally does not cover internal mechanical breakdown, wear and tear or consumables. Exact cover depends on the insurer's wording and any add-ons you buy.
Is CPM the same as motor insurance for a backhoe loader?
No. Machines registered for road use usually need motor insurance when they travel on public roads, while CPM focuses on damage while working at sites. Many owners of road-registered machines carry both. Speak to your insurer or broker to make sure there is no gap between the two.
How is the sum insured for CPM decided?
CPM is commonly written on the current replacement value of an equivalent new machine. If you insure for less, many policies reduce claims in proportion to the shortfall. Review the value with your insurer or broker at every renewal.
Why do maintenance records matter for an insurance claim?
Surveyors need to decide whether damage came from an insured accident or from wear and neglect, which is usually excluded. Dated inspection and service records with photos show the machine was looked after. Teams that keep inspection history in HVI can share that proof the same day.
How can I manage insurance for a whole equipment fleet?
Keep one record per machine with policy number, expiry date, sum insured, review date and inspection history, and set reminders before every renewal. That prevents lapses and keeps claim evidence ready. Book a demo to see insurance tracking alongside inspections in HVI.
Keep Every Machine Insured and Every Claim Strong
Track renewals and sum insured reviews, keep dated inspection and service records with photos, and have claim evidence ready the moment something goes wrong. Fewer lapses, fewer reduced claims and faster settlements.