Every excavator, crane and tipper starts losing value the day it is bought, and how you record that loss shapes your profit, your tax and the price you get when you sell. Many owners leave depreciation entirely to the accountant, then discover at resale time that the machine is worth far less than the books say, or far more because it was well looked after. This guide is general guidance only, so confirm rates with your chartered accountant, and HVI keeps the asset history behind every valuation.
Heavy Equipment Depreciation in India: Methods and Useful Life
Understand straight-line and written down value methods, how useful life is set, and why maintenance records can move the real value of a machine more than any formula.
Straight-Line vs Written Down Value
Both methods spread the cost of a machine over its life. They differ in how fast the value comes down in the early years.
| Point | Straight-line method | Written down value method |
|---|---|---|
| How it works | Same amount charged every year | Same percentage charged on the reducing balance |
| Early years | Moderate charge | Higher charge |
| Later years | Same charge as early years | Much smaller charge |
| Closer to resale reality | Less so for machines | Often closer, as machines lose value fastest early |
| Where it is used | Common in company books | Used in company books and required for income tax |
Book Value Over Nine Years: A Worked Example
An excavator bought for Rs 50 lakh with a 9-year useful life and a 5% residual value of Rs 2.5 lakh. Figures are rounded and for illustration only.
Useful Life Under the Companies Act
Schedule II of the Companies Act, 2013 gives indicative useful lives for company books. These are commonly cited figures for equipment categories. A company can use a different life if it has a technical justification, so check the current schedule and your auditor's view.
Residual value is normally taken as not more than 5% of original cost in company books unless the company justifies otherwise.
Keep the Asset History Your Accountant and Buyers Ask For
HVI records hour meter readings, inspections, services and major repairs for every machine, so book value, condition and replacement decisions rest on real data.
Book Depreciation and Tax Depreciation Are Different
Most companies keep two depreciation records for the same machine. One follows the Companies Act for financial statements, the other follows the Income-tax Act for tax returns.
Company books
- Follows Schedule II of the Companies Act
- Straight-line or written down value can be used
- Based on useful life and residual value
- Calculated for each asset
Income tax
- Written down value on blocks of similar assets
- Rates set by asset class in the tax rules
- Commercial vehicles used for hire often get a higher rate than general machinery
- Assets used for less than 180 days in the year of purchase get half the normal rate
Tax rates and rules change from time to time. Always confirm the current rate for each asset class with your chartered accountant before filing.
How Maintenance Records Change Real Value
Depreciation formulas do not know how a machine was treated. Buyers, lenders and valuers do, and they pay for proof.
- Complete, dated service history
- Hour meter readings recorded over time
- Regular inspection reports with photos
- Major components replaced on time and recorded
- Clean oil sample and fault code history
- Missing or patchy service records
- Hour meter replaced with no record
- Undocumented accident or engine repairs
- Visible neglect, leaks and worn wear parts
- No proof that statutory inspections were done
When Depreciation Meets the Replacement Decision
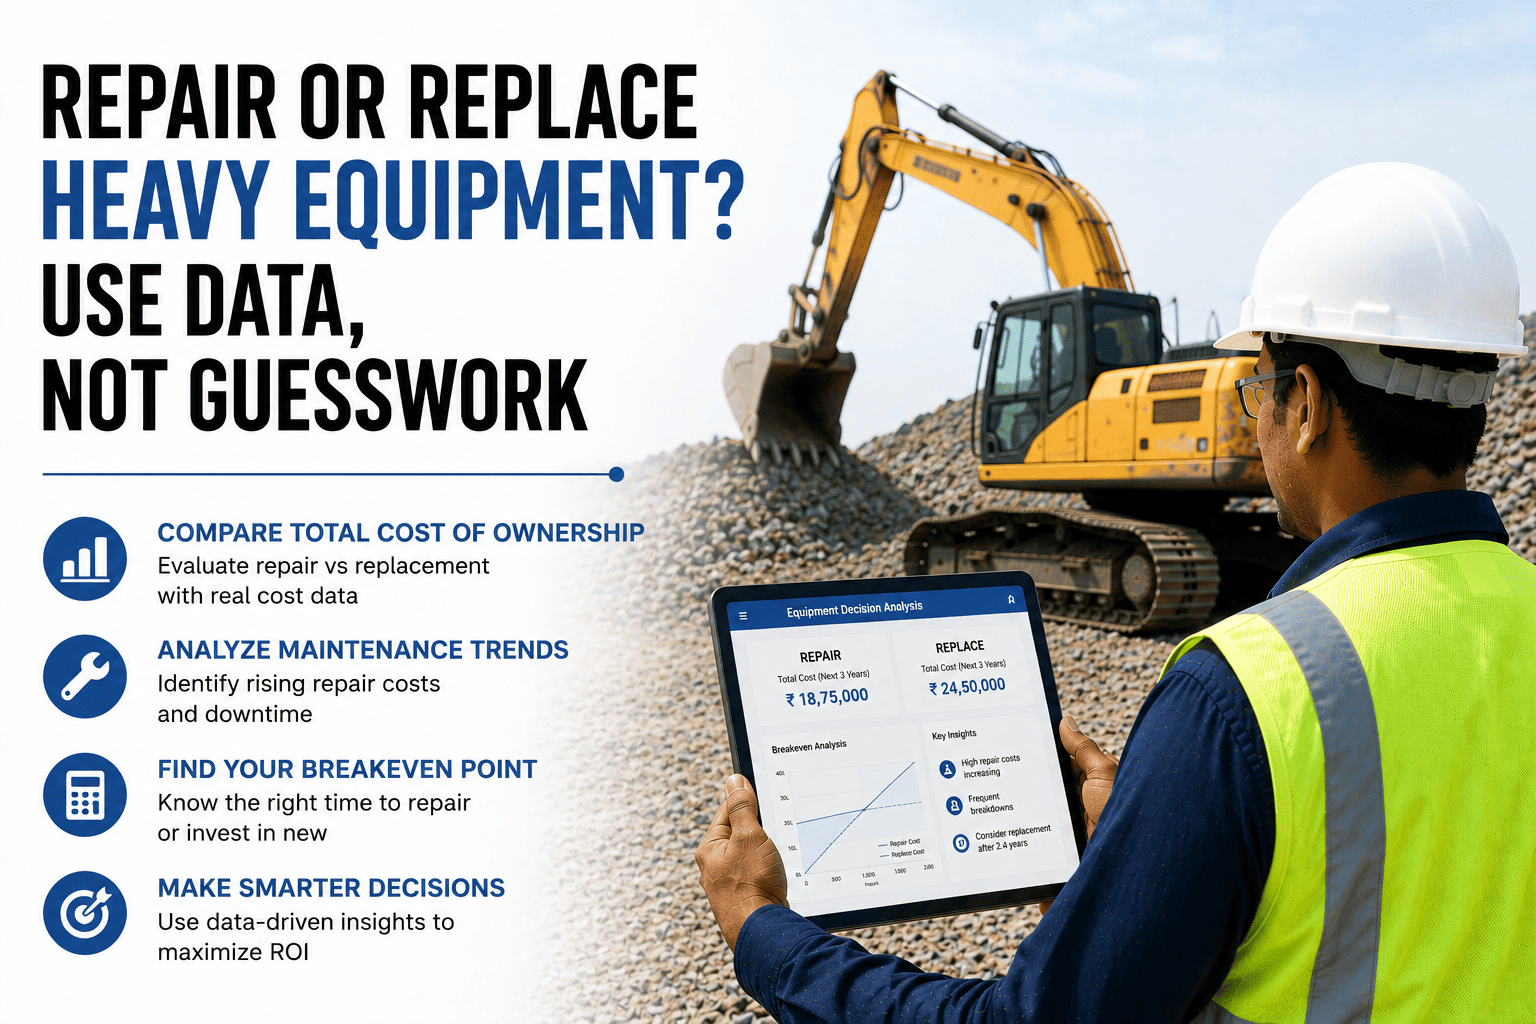
A low book value does not mean a machine should be sold, and a high one does not mean it should be kept. These signals matter more.
Rising repair cost
Yearly maintenance is climbing faster than the hire or work the machine earns.
Falling availability
More days lost to breakdowns, hurting jobs and customers.
Major overhaul due
An engine or transmission rebuild would cost a large share of resale value.
Resale window
Market value is still good because the history is clean and hours are reasonable.
An Asset Register That Supports Every Valuation
A sample view from HVI. Book values come from your accounts, while hours, maintenance cost and condition come from field records.
| Asset | Bought | Hours | Maintenance this year | Condition |
|---|---|---|---|---|
| EXC-01 | 3 years ago | 7,800 h | Within plan | Good, full history |
| CRN-02 | 6 years ago | 11,200 h | Rising | Review before overhaul |
| TIP-09 | 5 years ago | Odometer tracked | High | Replacement candidate |
| LDR-04 | 2 years ago | 4,100 h | Within plan | Good, full history |
Equipment Depreciation FAQs
Which depreciation method is better for heavy equipment?
Neither is better in every case. The written down value method charges more in early years, which often matches how machines lose market value, while the straight-line method spreads the cost evenly. For income tax, the written down value method on blocks of assets applies, so most companies use both for different purposes.
What is the useful life of an excavator in India?
Schedule II of the Companies Act gives an indicative useful life for earth-moving equipment used in civil construction, commonly cited as 9 years. A company can adopt a different life with technical justification. The real working life of a well-maintained machine can be much longer, which is why hours and condition records matter.
Does good maintenance change depreciation in the books?
Not directly, because book depreciation follows a set method and life. Maintenance changes the market value, which is what you receive when you sell, and it can support a longer useful life estimate. Teams that record service history in HVI can show buyers and valuers exactly how a machine was kept.
Why is my machine's book value different from its resale price?
Book value follows an accounting formula, while resale price depends on hours, condition, market demand and the strength of the service history. A well-documented machine can sell above book value, and a neglected one can sell well below it. Treat book value as an accounting number, not a price.
How can I keep better records for valuation and audits?
Keep one register per asset with purchase details, hour or odometer readings, inspections, services and major repairs, all dated. Share it with your accountant for depreciation and with buyers at resale. Book a demo to see an equipment asset register in HVI.
Protect the Value of Every Machine You Own
Record hours, inspections, services and repairs for every truck and machine in one place. Give your accountant clean data, make replacement decisions with confidence and sell with a history buyers trust.